Following the recent U.S. midterm elections, equity markets, particularly Artificial Intelligence (AI) stocks, are navigating significant volatility. This is partly due to the overwhelming adoption of measures that could lead to increased restrictions on data center expansion. Despite these immediate setbacks and uncertainties, the long-term outlook for the AI industry remains robust, with continued expansion anticipated. This article identifies three prominent technology companies – Apple, Alphabet, and Microsoft – as compelling investment opportunities. These stocks are recommended as strong buys on the current post-election dip, with a strategic five-year holding period advised. Each company is highlighted for its unique strengths, including diversified business models, strong financial performance, existing market leadership, and the capacity to adapt to evolving regulatory landscapes, positioning them to outperform the broader market over the coming half-decade.
1. Apple Apple's business is relatively insulated from potential AI industry headwinds, such as increased regulatory scrutiny on data center expansion, as it operates its own data centers but also strategically outsources some cloud workloads. The company demonstrates strong financial performance, with its latest iPhone driving a robust renewal cycle and recording double-digit sales growth for four consecutive quarters, reaching $114.5 billion in sales during Q4 2026. With the successful launch of innovative products like the iPhone Duo, Apple is expected to continue expanding its vast installed user base, increasing its high-margin subscription revenue, and achieving consistent long-term revenue and earnings growth, making it a resilient investment. 2. Alphabet Alphabet, a major hyperscaler, faces potential regulatory challenges from midterm elections that could impact data center expansion. This has led to significant AI investments and negative free cash flow in recent quarters, suggesting potential scaling back of plans if lawmakers crack down on data center growth. However, Alphabet is well-positioned for several reasons. Firstly, its business is highly diversified, with primary revenue still stemming from its dominant Google search engine and YouTube advertising platforms, which are undisputed market leaders. These segments effectively complement its growing cloud and AI endeavors. Secondly, a potential slowdown in new data center construction amidst sustained demand for computing capacity could enhance pricing power and margins for Alphabet's extensive existing infrastructure. This diversification and substantial existing capacity provide significant resilience against uncertainties, supporting an attractive long-term outlook across multiple fast-growing industries. 3. Microsoft Microsoft, another leading hyperscaler, is similarly poised to benefit from increased demand for existing compute capacity if the AI industry faces expansion restrictions. The company boasts a highly diversified business model, relying heavily on long-term software service contracts with millions of clients who depend on its ecosystem for daily operations. This is evident in its impressive $677 billion in commercial remaining performance obligations as of September 30, reflecting a 73% year-over-year increase. Microsoft anticipates recognizing approximately 30% of this backlog in the next 12 months, ensuring a steady revenue stream. This strong contractual revenue, combined with its strategic positioning in the evolving AI space and consistent demand for legacy services, ensures Microsoft is well-equipped to navigate potential industry headwinds and drive sustained sales and earnings growth. Furthermore, Microsoft's status as an excellent dividend stock provides an additional avenue for boosting investor returns over the next five years through dividend reinvestment.
1. Apple
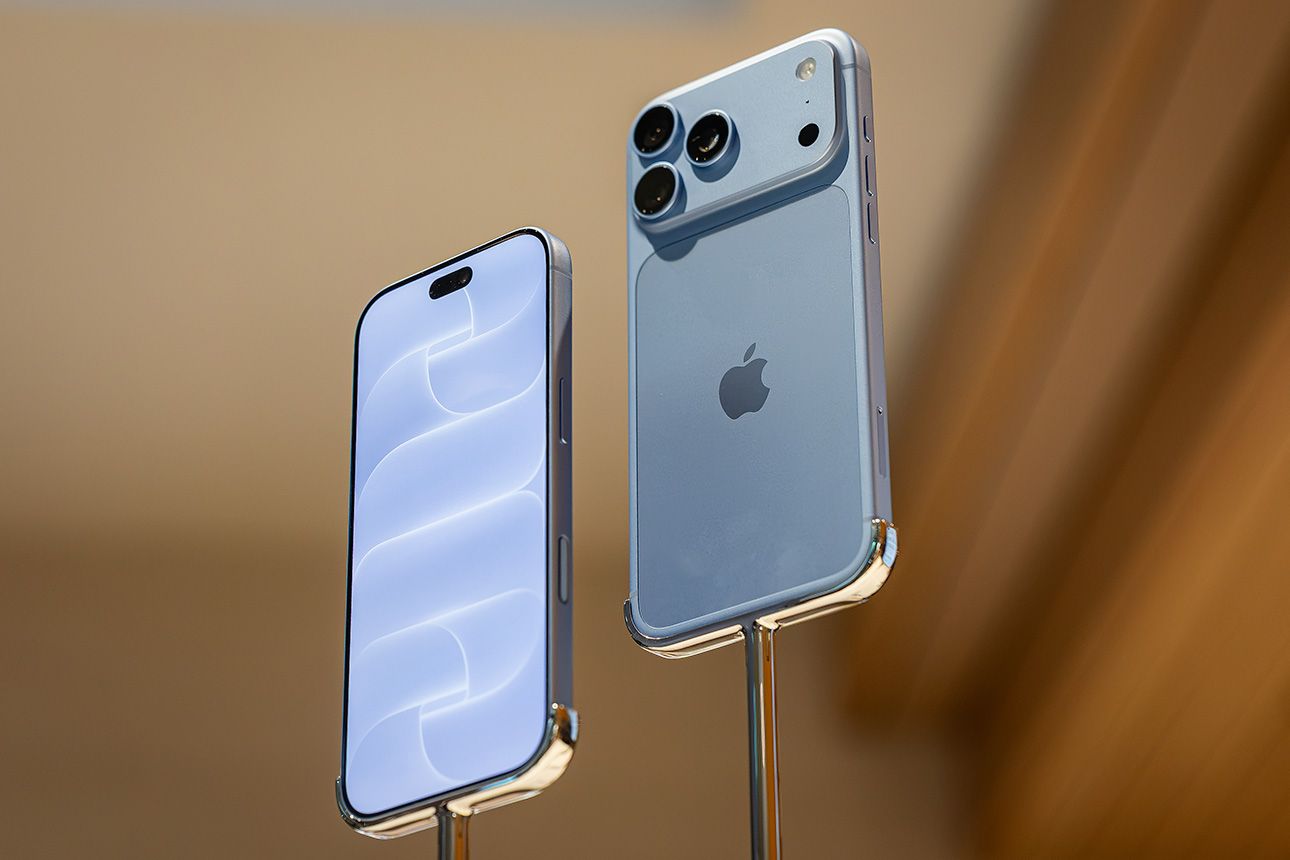
Apple's business is relatively insulated from potential AI industry headwinds, such as increased regulatory scrutiny on data center expansion, as it operates its own data centers but also strategically outsources some cloud workloads. The company demonstrates strong financial performance, with its latest iPhone driving a robust renewal cycle and recording double-digit sales growth for four consecutive quarters, reaching $114.5 billion in sales during Q4 2026. With the successful launch of innovative products like the iPhone Duo, Apple is expected to continue expanding its vast installed user base, increasing its high-margin subscription revenue, and achieving consistent long-term revenue and earnings growth, making it a resilient investment.
2. Alphabet
Alphabet, a major hyperscaler, faces potential regulatory challenges from midterm elections that could impact data center expansion. This has led to significant AI investments and negative free cash flow in recent quarters, suggesting potential scaling back of plans if lawmakers crack down on data center growth. However, Alphabet is well-positioned for several reasons. Firstly, its business is highly diversified, with primary revenue still stemming from its dominant Google search engine and YouTube advertising platforms, which are undisputed market leaders. These segments effectively complement its growing cloud and AI endeavors. Secondly, a potential slowdown in new data center construction amidst sustained demand for computing capacity could enhance pricing power and margins for Alphabet's extensive existing infrastructure. This diversification and substantial existing capacity provide significant resilience against uncertainties, supporting an attractive long-term outlook across multiple fast-growing industries.
3. Microsoft
Microsoft, another leading hyperscaler, is similarly poised to benefit from increased demand for existing compute capacity if the AI industry faces expansion restrictions. The company boasts a highly diversified business model, relying heavily on long-term software service contracts with millions of clients who depend on its ecosystem for daily operations. This is evident in its impressive $677 billion in commercial remaining performance obligations as of September 30, reflecting a 73% year-over-year increase. Microsoft anticipates recognizing approximately 30% of this backlog in the next 12 months, ensuring a steady revenue stream. This strong contractual revenue, combined with its strategic positioning in the evolving AI space and consistent demand for legacy services, ensures Microsoft is well-equipped to navigate potential industry headwinds and drive sustained sales and earnings growth. Furthermore, Microsoft's status as an excellent dividend stock provides an additional avenue for boosting investor returns over the next five years through dividend reinvestment.